Home Blog
Dental Was Uninsurable Because It Was Undocumented: How Image Data Changes the Underwriting Question
short answer
Dental insurance has historically been difficult to underwrite because treatment lacked consistent records, claims data and baseline clinical evidence. As dentistry becomes more organised and digital, intraoral images, X-rays and treatment records can create measurable risk profiles. AI can standardise this data, improve claims adjudication and identify existing conditions before coverage begins. This shift could make dental more priceable while shaping the future of OPD insurance in India.
There was a time when you could walk into a barbershop for a haircut and walk out missing a tooth. Through the Middle Ages and for centuries after, barbers doubled as dentists and surgeons. Trained physicians saw blood, teeth and sharp tools as manual work beneath them. Barbers had steady hands and the sharpest blades and pliers around, so they took the job. One visit could cover a shave, a trim and an extraction.
Then dentistry grew up. It became a profession with degrees, clinics, sterile instruments and digital X-rays. Today, a patient in India can get an implant, a root canal or clear aligners at a clinic down the road.
But one space is still catching up. The treatment evolved. The record did not. Much like in the barber's chair, most dental care in India leaves little behind on paper. That gap, not the risk itself, is why dental stayed outside insurance.
Why dental is excluded from health insurance
Ask an underwriter and you will hear that dental risk is too hard to price. That is true, but the cause is often misread. Dental risk was never especially bad. It was invisible. Here is what insurers have been working with:
- Care sits outside hospitals. Almost all dental treatment happens in outpatient clinics, while most Indian policies are built around hospitalisation.
- Payments are cash-first. Out-of-pocket spending leaves very little claims history behind.
- Outcomes go untracked. India has poor data on how often procedures fail, repeat or were needed at all.
- Notes are inconsistent. Two identical procedures can look nothing alike on paper.
- No baseline exists. Without a record of a member's starting condition, pre-existing issues surface later as claims.
So why dental is excluded from health insurance comes down to evidence, not appetite. Insurers cannot price risk confidently without claims and outcomes data. Dental insurance India underwriting has been guesswork, and guesswork gets priced defensively or not at all. Understand why dental is excluded from health insurance, and you understand what needs fixing.
From neighbourhood clinic to organised chain
For decades, Indian dentistry ran quietly on the edges of organised healthcare. A solo practitioner, a neighbourhood clinic, a patient who only walked in when the pain got bad.
That picture is changing. Slowly, but clearly. The biggest shift is structural. Dentistry is moving from standalone clinics toward an organised, chain-based ecosystem. Solo practitioners still handle most patient visits, yet chains are gaining steady ground in metros and Tier 1 cities.
Hospitals went through the same move after India's health insurance boom. Payers asked for standard codes and digital records, and the sector organised around them. Dentistry could be next.
How image data changes the underwriting question
Here is what most product teams miss. Dentistry already produces a rich clinical record. An intraoral photo or X-ray shows decay, bone loss, fillings and missing teeth. That is baseline risk, visible in a single image.
As clinics adopt standardised treatment codes, digital charts and consistent documentation, those images start becoming records. As a side effect, they also become exactly the structured data that AI dental diagnostics and India's annotation ecosystem need to grow. Better records train better models. Better models make records more consistent.
This is where structured clinical data insurance begins to work. The question shifts from "Is dental insurable?" to "What does this member's mouth look like today?" An underwriter can answer that. This is insurable risk dental, defined by evidence rather than assumption.
AI vs manual claims adjudication insurance
Manual review still carries a trace of the barber's chair. A reviewer checks a form, glances at an X-ray and makes a judgment call. Results vary by reviewer, by workload, even by the day.
AI reads every image against the same criteria. It flags gaps between claimed and visible treatment and leaves a trail anyone can audit. Humans still handle the edge cases. They just stop being the only line of defence.
The debate on AI vs manual claims adjudication insurance is really a debate about consistency. For dental, where evidence lives in images, AI vs manual claims adjudication insurance is less a choice than a matter of scale.
Future of OPD insurance in India
Dental is the clearest test case for a bigger shift. The future of OPD insurance in India depends on making everyday outpatient care fully documentable. Dental, with its image-led workflow, is the easiest place to prove it can work. Get the future of OPD insurance in India right in dentistry, and the playbook travels to every other outpatient category.
Dental was never uninsurable. It was undocumented. The record now exists, and the underwriting question has changed with it.
Where ToothLens fits in
ToothLens was built on one belief. Fix the record, and dental becomes priceable. ToothLens works across dental insurance in health insurtech India, from the benefit plans members use to the data layer that makes those plans underwritable.
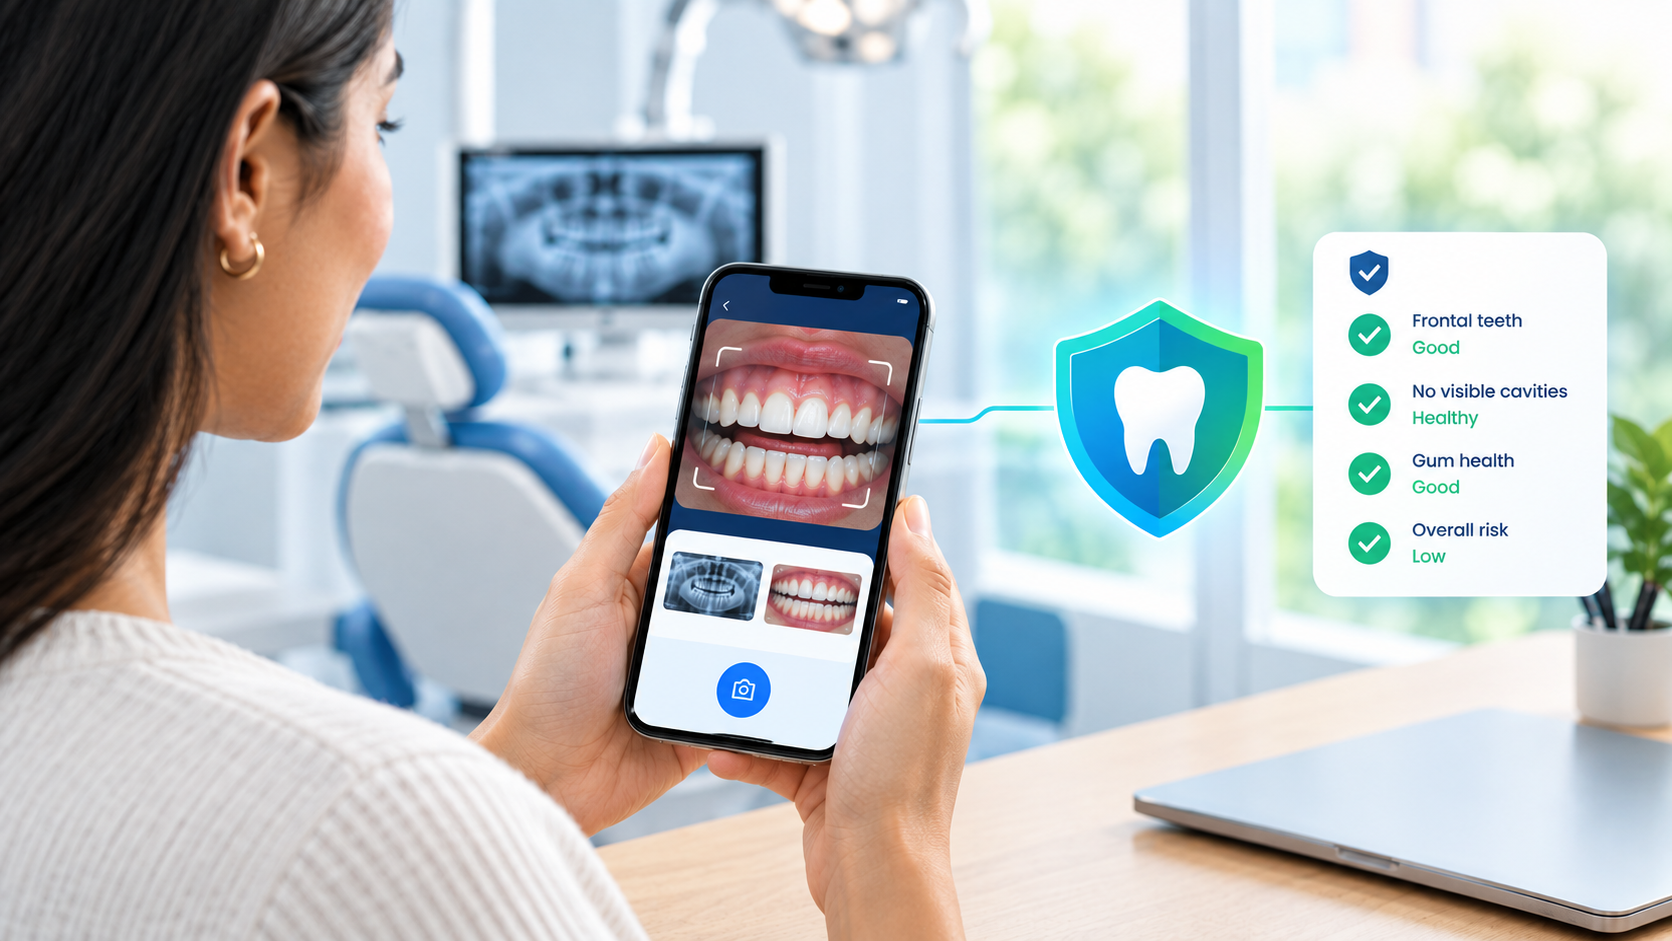
That layer starts with SmartCheck. SmartCheck is an AI dental risk-scoring engine that converts dental photographs and X-rays into standardised risk scores, giving insurers and TPAs underwriting intelligence at the point of onboarding. Put simply, it checks the teeth before the policy begins. Existing conditions show up on day one, not as surprise claims months later.